DPO Radio
ACTIVE
 Circular 46/2026/TT-NHNN Credit-Information Consent
Turn consent for credit-information reporting into a record you can print, reproduce and show an inspector, and tie each disclosure to the consent behind it.
If you are a credit institution, or you receive credit information in Vietnam, Circular 46/2026/TT-NHNN has changed how you evidence borrower consent since 1 November 2026. The State Bank of Vietnam issued it on 9 September 2026. It states no transitional provision. Whether a consent you already hold meets the amended text is a question for your counsel.
What has changed for you:
Circular 46 amends Circular 15/2023/TT-NHNN on the State Bank's credit-information activity. It does not replace it and has no repeal clause. Ten articles change, and the rest of Circular 15 still applies unchanged.
The Circular rests on the Law on the State Bank, the Law on Credit Institutions as amended by Law 96/2025/QH15, Decree 329/2025/NĐ-CP on the International Financial Centre, and the State Bank's organisational decree.
Circular 46 is an optional banking addition for one activity: reporting and sharing credit information through the State Bank's system. It sits beside the banking, fintech and payments overlay. That overlay covers the customer due-diligence, account and card rules for the borrower relationship the credit information comes from.
You work from two texts: Circular 15 for the regime, and Circular 46 for the rules that now govern consent, electronic supply and inspection. Circular 15/2023/TT-NHNN is not available as a separate framework in ComplianceOne. Instead, each Circular 46 record names the Circular 15 article it changes.
Where credit information is personal data, the Personal Data Protection Law and the Data Law also apply. This matters most for disclosures to a foreign credit-information organisation. The Circular requires the borrower's consent "in accordance with the relevant law", and does not say consent is the only condition.
| Provision | What It Requires | What You Need |
|---|---|---|
| Article 9, amending Article 17(1) | A credit institution ensures the borrower's consent to supply of credit information to CIC, under the Circular and personal-data protection law. The consent is clear, specific, and printable or reproducible in writing, including electronically or in a verifiable format | A consent record for each borrower naming CIC as recipient and the personal-data basis, with a copy you can produce |
| Article 6, adding Article 12(7) | Supplying a borrower's credit information to voluntary participating organisations, foreign credit-information organisations or other organisations needs that borrower's consent under the relevant law, in the same form, and compliance with the contract with CIC | A separate consent record for each onward recipient class, with the CIC contract clause beside it |
| Article 6, amending Article 12(6) | The sixth recipient class reads "other organisations (if any)" | Every disclosure classified by recipient class: CIC, voluntary organisation, foreign credit-information organisation, or other organisation |
| Article 4(2), amending Article 9(3) | Credit information is supplied as electronic data under the Credit Information Indicator System. Written supply is allowed only for indicator groups that cannot go electronically, by agreement with CIC | Each written-supply exception recorded per indicator group, with the CIC agreement that supports it |
| Article 5, replacing Article 10 | Credit institutions supply at the frequency set in the Indicator System issued with the Governor's Decision. Voluntary organisations supply at the frequency in their contract with CIC | The frequency you are bound to and its source. The Circular sets no period of its own |
| Article 4(1), amending Article 9(1)(i) | Annual financial statements of corporate borrowers, as filed with the tax authority or audited. Foreign borrowers report under IFRS or home-country standards | The basis of each statement, in the data-category record |
| Article 2, adding Article 3(3a) and amending Article 3(4) | International Financial Centre member banks enter the regime. Their related persons are determined under Decree 329/2025/NĐ-CP | A record that you are a member bank, and the Decree 329 definition applied |
| Articles 7–8, amending Articles 14–15 | The SBV Inspectorate leads inspections with CIC. Regional branches inspect locally. Member banks are inspected under the Centre's rules. CIC is the focal point for the Centre's supervisory body | Consent, disclosure and supply evidence you can produce to whichever body inspects |
| Obligation | Timeline | Reference |
|---|---|---|
| Circular in force | Since 1 November 2026 | Article 11(1) |
| Consent before supply to CIC | Consent must come first; no period is set | Article 9 |
| Consent before onward supply to a voluntary, foreign or other organisation | Consent must come first; no period is set | Article 6(2) |
| Supply frequency | Set by the Indicator System Decision or the CIC contract; no period in the Circular | Article 5 |
The Circular states one date and no other numeric period. ComplianceOne does not add a consent-capture window, a retention period or a withdrawal deadline that the Circular does not contain.
The Circular prescribes no form, no consent template and no consent channel. It sets a standard instead: consent must be clear, specific, and printable or reproducible in writing, including electronically or in a verifiable format. "Verifiable format" is not defined. The Credit Information Indicator System is a separate Governor's Decision and is cited, not reproduced.
Every record ComplianceOne supplies for Circular 46 is an internal template and is labelled as one:
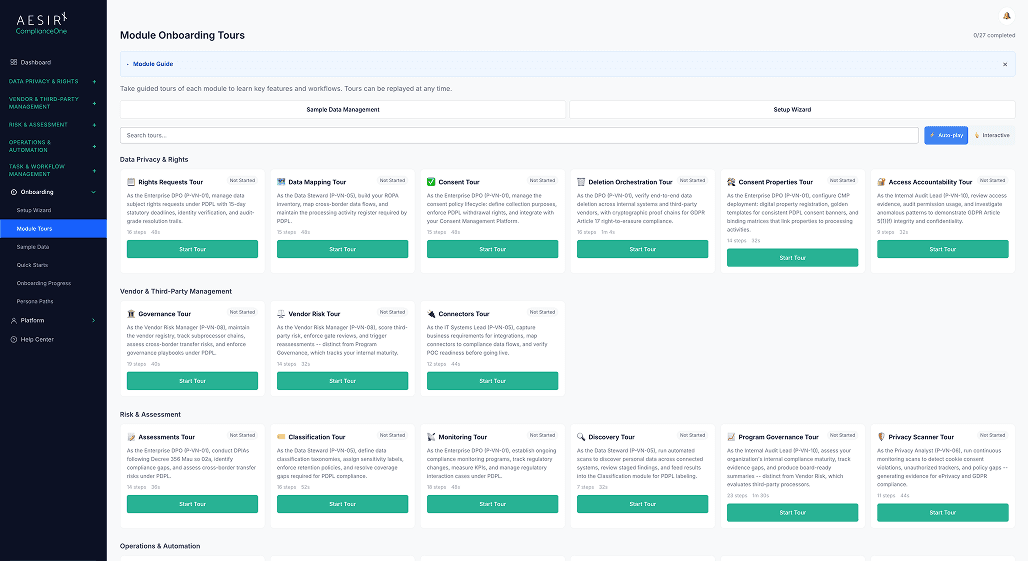
Circular 46 is available in the Enterprise Unlimited package, through the Sector Overlays module, whether installed directly or for reference. Once Circular 46 is added to your workspace, you work from eleven requirements. Each names the Circular 46 article and the Circular 15/2023 article it changes. ComplianceOne shows the Circular as active, in force since 1 November 2026.
Consent as evidence, not a flag. Each consent record holds the consent text and version, the credit-data categories covered, the recipient or recipient class, the purpose, the timestamp, the channel, and the printable or reproducible copy. It also notes which format you rely on as verifiable. A consent text naming only CIC supports only supply to CIC; to cover onward recipients, the text must name them. You manage consent on the Workflows and Purpose Catalog pages in Consent, and record what a withdrawal reaches on the Withdrawal Propagation page.
Disclosures by recipient class. Each register entry points to its consent record and the CIC contract clause. A disclosure to a foreign credit-information organisation also points to the transfer review it relied on. ComplianceOne treats the sector consent as one transfer condition, never a substitute for the conditions in the Personal Data Protection Law and the Data Law. You record those on the Transfer Assessments page in Assessments.
Supply rules with their source. The written-supply exception and your supply frequency are recorded with their source. An overdue supply is measured against the instrument that actually sets the period.
Ready for inspection. The inspection readiness index gathers what the SBV Inspectorate, a regional branch or the International Financial Centre's inspection body would ask for.
 Consent Governance
Holds the versioned consent text, consent records by recipient class, and the withdrawal-propagation check
Explore Consent Governance Data Mapping
Records the credit-information data categories, the disclosure flows to each recipient class, and the basis of corporate financial statements
Explore Data Mapping DPIA & Assessments
Records the cross-border transfer review before a disclosure to a foreign credit-information organisation
Explore DPIA & Assessments Governance
Holds voluntary participants, foreign credit-information organisations and other recipients, with the CIC contract clause each supply relied on
Explore Governance Audit Trail
Keeps every change to a consent record, a disclosure entry or a transfer review for inspection
Explore Audit TrailCircular 46 is in force. Confirm that:
See how ComplianceOne holds a reproducible borrower consent, separates disclosures by recipient class, and requires a transfer review before a foreign disclosure.
Ronni K. Gothard Christiansen - Technical Privacy Engineer & CEO
Technical Compliance Expert, 32+ Years Open Source Advocate, X-BoD Open Source Matters Inc.
No. It amends and supplements ten articles of Circular 15/2023/TT-NHNN and has no repeal clause. Circular 15 remains the working instrument. Cite every obligation to both the amending article and the article it changes.
The amended text requires consent that is clear and specific, and that can be printed or reproduced in writing, including electronically or in a verifiable format. A general notice the borrower may not have read, a bundled clause or a database flag fails at least one of those tests. Whether a particular consent is enough is a legal judgement, and ComplianceOne records what you relied on so you can make and defend it.
The Circular requires the borrower's consent for that supply, in line with the relevant law, and does not say consent is the only condition. Where the credit information is personal data, the cross-border conditions of the Personal Data Protection Law and the Data Law also apply.
Whether a withdrawal stops future supply to CIC, only the onward disclosures, or neither, is a legal question under the Circular, the Law on Credit Institutions and the Personal Data Protection Law. ComplianceOne records counsel's answer and tests that the disclosures it reaches are stopped. It does not decide the answer.
No form is annexed, and no consent template or channel is prescribed. The only date in the Circular is its commencement on 1 November 2026. Supply frequency is set by the Indicator System Decision and the contract with CIC.

Test your consent inventory against the reproducibility standard, your disclosure register by recipient class, and the evidence an inspection would ask for.

Review which consents you hold are in question, and which onward disclosures need a transfer review.

The evolution of Aesir is Aesir +  (the Norse symbol for Necessity)"Needed in order to achieve a particular result"
♥Join the AesirX Privacy Newsletter. Stay Informed. Stay Compliant.